Cash-flow shortages are common in business, but they do not all mean the same thing.
A profitable company can temporarily run short of cash because customers have not yet paid, a large expense has fallen due, inventory has been purchased ahead of a busy period, or the business is growing faster than its cash reserves can support.
In other cases, however, repeated cash shortages can indicate a more fundamental problem with margins, expenses, debt or the underlying business model.
For business owners, the important question is not simply, “How do I get more cash?” It is understanding why the shortage exists in the first place.
Here are some of the factors that can help distinguish a temporary cash-flow gap from a deeper financial problem.
1. Start With the Reason Cash Is Tight
The first step is identifying exactly what caused the shortage.
A temporary cash-flow problem usually has an identifiable cause. Perhaps several large customer invoices are outstanding, a seasonal business has entered its quieter period, or the company has made a significant inventory purchase ahead of expected sales.
These situations can put pressure on available cash without necessarily indicating that the business itself is performing badly.
A more concerning situation is when the owner cannot identify a specific reason for the shortage. If revenue is coming in normally but the business repeatedly struggles to meet ordinary expenses, the underlying numbers deserve closer examination.
2. Look at Accounts Receivable
One of the clearest examples of a timing-related cash-flow problem occurs when a company has generated revenue but has not yet collected the money.
A business might complete $100,000 worth of work during a month, but if customers have 30-, 45- or 60-day payment terms, that revenue does not immediately become available cash.
Meanwhile, payroll, rent, suppliers, insurance and other operating expenses still need to be paid.
This can become particularly noticeable when a company is growing. Higher sales may actually increase short-term cash requirements because the business must fund the cost of delivering more products or services before collecting from customers.
Owners should therefore monitor not only total receivables but also how long invoices remain outstanding.
If receivables are growing alongside sales, the problem may primarily be one of timing. If receivables are stable but cash continues to disappear, the cause may lie elsewhere.
3. Check Whether the Business Is Actually Profitable
Cash flow and profit are related, but they are not the same thing.
A profitable company can experience a cash shortage. However, a company that consistently spends more to generate sales than it earns will eventually face a much more serious problem.
Business owners should review gross margins and operating margins rather than focusing exclusively on revenue.
For example, increasing monthly sales from $200,000 to $250,000 sounds positive. But if discounts, labor costs, supplier prices and other expenses rise even faster, the additional revenue may contribute very little cash to the business.
If margins remain healthy and the cash shortage can be traced to payment timing or a specific temporary expense, the situation may be manageable.
If margins are steadily deteriorating, simply injecting additional cash may not solve the underlying problem.
4. Determine Whether the Shortage Has an End Date
A useful question is: when should the cash-flow problem resolve itself?
Suppose a company is waiting for $75,000 of confirmed customer payments over the next 30 days. The business may have a reasonably clear picture of how the shortage will be resolved.
The same applies to seasonal businesses. A retailer may intentionally build inventory before its strongest selling period, temporarily reducing available cash.
These situations have identifiable events that should restore liquidity.
A recurring shortage with no obvious end date is different. If the business needs additional money every month simply to cover ordinary operating expenses, the owner should investigate the cause before taking on additional financial obligations.
5. Examine Existing Debt and Repayment Obligations
Existing financing can significantly affect cash flow.
A company may appear profitable on its income statement while substantial loan, equipment or other financing payments consume much of the cash generated by operations.
Owners should calculate how much cash is leaving the business each week and month for existing obligations.
This becomes particularly important before taking on additional financing.
When a cash-flow shortage is temporary and the underlying business remains healthy, financing can sometimes provide additional breathing room. Depending on the company’s circumstances, business term loans may be one option to consider for planned expenses or investments where the business can comfortably manage a defined repayment schedule.
However, financing should support a viable business need rather than simply postpone a deeper financial problem.
6. Look for a Pattern
One isolated cash-flow shortage may not be particularly concerning.
Repeated shortages are more important.
Review the previous six to twelve months and look for patterns. Has the company struggled to make payroll several times? Are suppliers regularly being paid late? Is the business repeatedly using future revenue to cover today’s expenses?
If the same problem keeps returning, it is worth determining whether the cause is poor collections, inadequate margins, excessive overhead, debt obligations or insufficient working capital for the company’s current size.
Patterns often reveal more than a single month’s financial statements.
7. Build a Short-Term Cash-Flow Forecast
One of the most useful tools for diagnosing a cash-flow problem is also one of the simplest: a short-term cash-flow forecast.
Start with the cash currently available.
Then estimate expected incoming payments and outgoing expenses for each of the next several weeks.
Include customer payments, payroll, rent, supplier invoices, taxes, insurance, debt repayments, inventory purchases and any known one-time expenses.
This provides a clearer picture of when cash is likely to become tight and whether the problem should correct itself.
It is also worth creating a more conservative version of the forecast. What happens if an important customer pays two weeks late? What if sales are slightly lower than expected? What if an unexpected repair costs $10,000?
A business that remains financially stable under reasonable downside scenarios is in a very different position from one that requires everything to go perfectly just to meet its obligations.
8. Be Careful About Using Financing to Solve the Wrong Problem
Access to additional capital can be valuable when the underlying business is healthy and there is a clear use for the funds.
It can help bridge timing differences between receivables and expenses, fund planned expansion, purchase equipment or support other investments expected to produce a return.
But financing cannot make an unprofitable business profitable by itself.
If a company is consistently losing money because prices are too low, expenses are too high or demand is declining, additional borrowing may simply delay the point at which those problems have to be addressed.
Before seeking additional capital, owners should therefore understand both the immediate cash requirement and the reason it exists.
Temporary Cash Problem or Warning Sign?
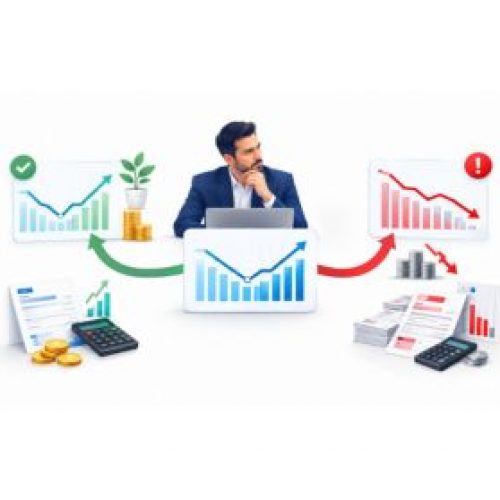
The distinction ultimately comes down to the health of the underlying business.
A temporary cash-flow shortage generally has a specific cause, a reasonably identifiable end point and a business capable of generating sufficient cash once the timing issue passes.
A deeper financial problem tends to repeat itself. It may be accompanied by shrinking margins, increasing debt, consistently late payments or operating expenses that regularly exceed the cash generated by the business.
Understanding that distinction allows owners to make better decisions.
Sometimes the appropriate response is improving collections or building a larger cash reserve. Sometimes expenses need to be reduced or pricing reconsidered. And in the right circumstances, additional financing may help a healthy company manage a temporary gap or invest in growth.
The important part is diagnosing the problem before choosing the solution.